Thursday, August 21, 2014

Where does the money go -- Book industry edition


In the previous post we took a look at the Amazon/Hachette dispute, and did so in a way that sought to add context to a feud in which one party was often characterized as the ‘good guy’ and the other as the ‘bad guy'. As with most things, it’s more complex than that, particularly as the book publishing industry attempts to steady itself on the choppy waters of the shift from physical to digital products and services.

Source: PWC

As hard copy print declines in popularity and eBook sales rise, the profit margins of publishers also stand to slide. When you’re not in the business of making, shipping, and selling things that occupy physical space in boxes, warehouses, and stores, it’s a whole different game. The pricing model of the legacy system looks something like this:

A new hardcover book now usually retails for $27.99. The pie chart below provides a rough guide to how those dollars are divided up between publisher, retailer, author, and agent. Not all authors have agents, but authors dealing with the major publishing houses generally do and for their services agents receive 15% of the author’s royalty rate. Note that these are not carved in stone numbers, but according to a source in the publishing industry, who I ran them past, they’re accurate, give or take a percent here or there.


It always helps to add some notes to such numbers, so here we go:  


Note that absent from this breakdown are fees paid to designers, printers, wholesalers, warehousers, shippers,  and publishing house staff. Those costs tend to come out of the publisher’s piece of the pie and when added up leave the publisher with about 10 - 12%.  

And then there’s the bookseller/retailer, who appears to be helping him/herself to an oversized slice, but rest assured, overhead in retail is high – leases, staff, equipment, advertising, etc.  (Ask yourself: when was the last time you met a wealthy bookstore owner...meaning one that became wealthy from selling books, not dabbling in retail for fun or philanthropic purposes).

Also note that the 10% paid to the author (minus 15% to the agent) is paid after the advance – the money the publisher paid the author before the book was actually written -- is paid back to the publisher.  

And finally, to cap off our notes section, it’s worth mentioning that the dollar pie, as split above, does not include any rights the author and/or agent have retained for licensing merchandise, foreign markets, or dramatic use (e.g. film adaptation).

Wait!!


After this post went up last night I heard from a friend who is a veteran of the New York and Boston publishing industry (who preferred to remain anonymous) and he added the following way of looking at the flow of dollars, so I'm sharing those notes with you here.

Using the same suggested list price of $27.99 for a book the numbers can be broken down this way:

The book is sold by the book publisher to the bookseller, or retailer, at a 'discount' of 50%. In other words, the publishing company gets $13.50 of revenue and the retailer then prices the book for sale in his/her store at a level at which costs can be covered and (hopefully) some profit margin can be obtained. Of the $13.50 now in the book publisher's pocket the dollars are divided as follows:


So, working with these numbers we have about $2.50 going to the author and about $0.50 to the agent, per book sold. Again, these payments would be after any advances made to the author have been recovered from actual sales of actual books. Until such time the book publisher is fronting all the cash. Of the approximately $10 the book publisher now has in cash flow, project expenses are paid (copy editing, book design, proofing, printing, shipping, etc)  as well as overhead (rent, staff, equipment, insurance, the electricity bill, any Keurig pods in the kitchen, etc). 

Is that everything? Not quite. The books the publisher sells to the retailer aren't really sold. They're consigned. Meaning that depending on the deal struck, the retailer can return unsold inventory to the publisher, in which case the publisher will be issuing a refund to the retailer. 

The other things that can happen: 

- The books that didn't sell at full price remain in the store, but move from the nice neighborhood, i.e. the window display or attractive tables at the front of the store, to the grab bag that is the remainder table, where they're usually priced between two and ten dollars. 

-The books get sold by the retailer to an overstock company, such as a discount store (Marshall's, Winners) or dollar store. 

- The books get 'pulped', or destroyed, which in the past probably meant landfill and today means shredded and recycled.


Now that we have two sets of data on the dollars, albeit with some variation, we can agree on this: the pie charts above shows us the book industry as it’s been for the past several decades. Like the rest of the creative industries, where outcomes are impossible to know until they actually happen, it’s a high risk/high reward system. Major book publishers, not unlike music labels and movie studios, have to put up capital in the hope that they will turn a profit, even though in all of these industries the general rule of thumb is that about 95% of projects taken on do not break even. If anyone really knew anything would JK Rowling’s manuscript for Harry Potter have been rejected 12 times? And would Penny “Laverne” Marshall have received a hefty $800,000 advance for her memoir, which ended up selling 17,000 copies. Using our newly acquired skills in book industry math, that level of sales constitutes a small fraction of what the publisher would need just to get back to $0.

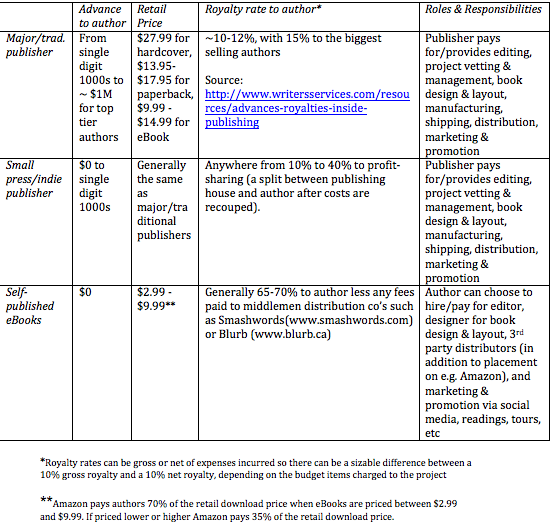
The next question in our analysis: how do these numbers change when we look at small press or indie publishers? Or when we consider the new possibilities in the publishing marketplace, such as bypassing hard copy altogether and going the route of the self-published eBook? There's a chart for that -- primarily because I whipped one up -- and here it is:
Click to enlarge


And a few notes regarding these numbers:

The number of copies to break even can be a few hundred for a self-published eBook (no advance to repay), approximately 1500 to a few thousand for an indie press book (advance of zero to a few thousand), and ten thousand plus for a title with a major publishing company (assuming an advance in the low tens of thousands).

On average --  and averages in cases such as these can be charitable,  because they also include the numbers at the top end -- this is what sales figures look like:

The average book published sells 250 copies per year and 3,000 copies over its lifetime. In other words, it loses money. And even at that level we’re talking about the top 10% of all books published. 90% of books published sell fewer than 100 copies per year. For eBooks, average sales are estimated to be 100-150. And that's total lifetime sales, though admittedly we're still in the early days. And while the major eBook retailers (Barnes & Noble, Amazon) do not publish statistics on eBook sales (whereas they do for print books), this conscientious blogger ran the numbers forensically and came up with a figure of $297 for the average eBook royalty paid to authors in 2013.

Which brings us to the grand finale of this post on books and bucks. When we take the whole picture into account – let’s use the approximately 1 million books published each year in the U.S. because it’s an easy landscape to work with and it's the world's largest book market – this is how the dollars shake out:

With a single digit percentage of authors published by major houses making something resembling a barebones living wage ($40,000 or more), and the biggest proportion of authors being those that self publish. Though the chart below shows this group as earning $1 - $4,999 per year, I think that after taking into account the other numbers in this post it’s safe to assume that the actual dollars in pocket come closer to covering the cost of a take-out meal, as opposed to, say, a really nice couch. (Source: Digital Book World 2014 report)

Click to enlarge

So there you have it for the basics of the book industry numbers. Remarkably similar to the music industry, as examined in detail on this blog last year.

In Part 3 of this post we take a look at the size of the overall eBook market, which will set the stage for Part 4, when we’ll go beyond the big publishers and big retailers, and look at some of the new players in the publishing industry as it transitions from a high barrier to entry hard copy based business to a low barrier to entry digital one. Is it meet the new boss, same as the old boss? Or are we better off than we were in the world of a handful of gatekeepers, many aspirants, and a relative few selected for a promenade in the marketplace?

Oh, and there's even a Part 5, in which we take a closer look at case of the initially self-published 50 Shades of Grey, and how its author, E.L. James became the world's top earning author just a couple of years after she first tried her hand at writing.

Thursday, August 14, 2014

It's not just about Amazon vs Hachette


So much digital ink has been spilled on this topic.

And our brains love binaries, the things that can be reduced into two opposing ideas. So naturally we want to think that in the publishers vs. the web giant sweepstakes one side is “good” and the other is “bad”, one is “right” and the other is “wrong". It makes it all seem like we live in a rational world where there are easy answers and, really, who doesn't like that.

Well it turns out it’s not only about Amazon vs. Hachette. It’s really about the individual creator in the new marketplace. What is actually on the table is a combination of the following: the new opportunities available to writers today, the new kind of hustle required to be in the game, and the forces of reintermediation that are at work. These are the new middle men -- the search engines, the content aggregators, the social networks, the e-tailers, and the distributors -- or, in other words, the channels through which all digital information now flows. The original promise of the Internet was one of of a massive decentralization of power. Any one, regardless of size, opinion, or financial resources could have a digital presence. And that remains true. But what is also true is that in the digital environment we also  have oligopolies, not unlike the 'big 4' or 'big 5' model of the analog world, in which a handful of companies dominate an industry. 

When it comes to discussions of creative content and the Internet we should probably know better. 15 or so years have elapsed since the music industry became the first major casualty of the digital environment. See that gigantic waterslide to the left? Those are global revenues from the sale of music from the late 1990s until more or less now. And that’s with the things that have staunched the bleeding, the most significant of which would be the appearance of the iTunes store in 2003 (that would be the momentary plateau in the graph). After years of lawsuits -- between labels and artists, between labels and fans, between artists and fans -- perfect hindsight shows us that though a certain amount of creative destruction definitely takes hold when technologies shift dramatically, so does a substantial portion's willingness to pay, provided the price point is right and the devices and systems for doing so provide people with what they want and are ridiculously easy to use. But don't expect customers to believe in the need for the customs of the analog world, such as bundled products and services, the cost of manufacturing, warehousing, and shipping things that come in cases and boxes, incremental costs (i.e. the cost of creating more than one 'unit', of something, which in the digital environment is close to zero), and the complete unknowability of audiences. Things are different now, and they're going to continue to look less like the past and more like something that we don't yet fully understand.

And yet, in many ways, very little from the learnings of the music industry in the digital age has made an impact on related industries. Consumers are still often paying analog prices for digital goods and services, being offered bundles when singles could be easily made available, and are having to wait for release dates set by industry, even though the constraints that were the reasons for delayed release dates no longer exist. So, the other day I posted an article from the Financial Times entitled “Authors should back Amazon in the battle with Hachette” to my Facebook page, mentioning that the publishing industry may be in the same place the music industry was over a decade ago, and how that may well be a good thing for us all, as we now have the benefit of several cycles of missteps and better steps to point to. Note: paywall may be in effect in the link, so I’m excerpting what I think is the pivotal issue from that article, and that’s the identification of the value chain, or stack as it’s sometimes referred to (interesting that one uses a horizontal metaphor and the other uses a vertical one), as a way of thinking about the processes involved. Whether that 'publishing' is books, music, magazines, or even online video, the idea of discrete nodes of value that can be snapped apart, lego style, and moved out of the control of the traditional intermediaries is key.

From the Financial Times article:

What matters to the success or failure of a book is the quality of conception and execution of the underlying project, the competence of the editing, and the effectiveness of marketing and promotion. Most new self-published titles fail these tests; in particular, the lack of a competent editor is often obvious. But this is also true of many titles now published by established houses.

Some existing publishers will thrive on the basis of their strengths in author support services. But most will not. Savvy and well-advised authors, often helped by agents, will be able to buy editing and marketing skills with the receipts from a much larger share of the sales proceeds than the traditional royalty model allows. One of the lessons of the new world of music is that the balance of revenues has shifted from publishing rights to live performance and merchandising. The blockbuster advance for authors will be replaced, as has to some degree happened in music, by securitisation of future revenue streams. Venture capital funding of book projects – perhaps starting with university textbooks and practitioner handbooks – is possible.

The post led to a flurry of comments by two people in particular. One, a veteran of the indie publishing industry and host of a podcast about books, and the other a photographer and author now working outside the system of publishers and advances and able to make things work to his advantage.
  

It's helpful to look at the value chain -- or stack, your choice of orientation -- and see the various tasks usually handled by publishers that writers now have the option to handle themselves, or hire someone to handle on their behalf. 


The big cut that publishers in these industries take was, at one time, essentially a kind of tax creatives had to pay for the substantial investment companies had to make to be book publishers, music labels, film studios, and the like. It took millions of dollars and years of relationships and much specialized knowledge to navigate those industries, so getting past the gate came with a steep price. Now, less so. But these are the best of times (anyone can get in) and the worst of times (again, anyone can get in). 

And now, with a non-binary mindset, I invite you to listen in on the conversation..sort of a textual podcast, brought to you here with the blessing of the discussants of course.


                                        Note: The article referenced above can be found here.


And that's how it can be done. Vigorous discourse, and without any flaming or shaming. I hope you've enjoyed this bout of electronic eavesdropping and that you'll click through for Part 2 of this post. We'll look at the financial pie of the traditional vs digital book industry, in Part 3 we sharpen our pencils and size up the eBook market as a whole, in Part 4 we look at some new approaches being tried out by publishers big and small, and in Part 5, how the initially self-published author of 50 Shades of Grey accomplished in 2 years what took other authors decades.

Opinionated content bonus: This writer says Amazon is doing us all a favor in its efforts to squeeze out the Big 4 of the book publishing industry. Click here for more.

Wednesday, July 16, 2014

Beauty & the blog (or how a quirky girl is beating the brands at their own game)

For centuries we had more or less a singular notion of female beauty, based largely on Western Anglo-Saxon features and symmetry. Some have even mathematically mapped the configuration of facial beauty.


As per the diagram above, what we see as beauty has a geometric structure, and it turns out, formula. To adhere to the ideal you should have no more than x number of inches between your eyes, y inches between nose and mouth, cheeks should conform to some sort of Pi R squared formula, etc. And after all the calculations a standard of beauty was produced that was widely circulated, and then accepted by most as ‘the’ standard. As media forms proliferated – first print, then television and film – the standards of beauty didn’t change all that much. Yes, things slowly expanded to include more ethnicities and nationalities, but generally mainstream beauty had a definition that was shared across continents for decades, if not centuries.

And then we entered the fast lane. As it has done with so many things, the Internet has enabled a broadening of standards and definitions of beauty. This is primarily because those who previously did not have a voice in the conversation – namely those who did not fit into the pre-ordained categories – were now able to have a voice, and a publishing platform. It started with websites and then expanded to blogs, YouTube channels, and proliferated rapidly and voluminously with Twitter, Pinterest, and Instagram accounts.

How large is this cohort of which I speak? I can’t seem to find a tally of the number of beauty blogs on the Internet, but I think a safe estimate would be tens of thousands to hundreds of thousands worldwide. There is data that indicates that onYouTube, beauty-related channels represent 15 billion cumulative views, growing at rate of around 750 million to 800 million views per month, putting such video channels in the ranks of some of the most popular ones out there.


Several things are interesting about these statistics. For one thing, brands (e.g. Revlon, L’Oreal, etc) account for around 3% of these views. And that is not for lack of trying. These companies spend not trifling resources and dollars creating videos expressly for disemmination online, but on average, such videos receive views in the thousands.

As an example, the screen shot below is taken from L’Oreal’s YouTube channel for its U.S. based business, and was grabbed in mid July 2014. It shows the range of videos, and the view count, for videos uploaded over the past two months.

Click to enlarge

Some quick math: That’s 39,221 views, across ten videos, for an average of 3,922 views for each one. And some more quick math: if beauty-related videos are being watched at a rate of 800 million views per month and L’Oreal, one of the world’s largest cosmetic firms, is pulling in just a few thousand views per video on average, then the bulk of the views are probably coming from somewhere else.

But this is not an unsolved mystery. The overwhelming majority, as in 97% + of the views, are coming from videos created by an army of bloggers and vloggers, many of which are 1-person shows, operating from their couch or bedroom, with a camera that probably cost less than $20. No scripts, no directors, no budgets. Just talking to camera about their purchases, their finds, and tips and tricks. A portion of these bloggers have sponsorship deals with cosmetic companies, which means they get sent products to use and review (and are required to disclose as such when that’s the case). There are an elite few who are stars in the field, such as Michelle Phan, featured in this earlier blog post, but for the most part beauty bloggers are as various as shades of nail polish and most are unknown except among their cadre of devoted followers.

As readers of this blog will know, I have a particular interest in the unusual and off-center, the things that can and/or do first get exposure, and then a following, on the self-serve audio, video, and text platforms that are now part of our everyday online experience. This is a new phenomenon because previously these people could not get into the system, let alone have the chance to find their audience. Hence my interest in tracking the journey from the margins to niches and then sometimes to thriving niches, and once in a while beyond that to large scale success.

I have turned the blog spotlight on such people in the past and today, another person of interest: 20-something Texan Bunny Meyer. She blogs under the name Grav3yard Girl and in no way does she conform to the industry’s definitions of beauty, grace, and artifice. Bunny presents herself unglamorously more often than she does glamorously, and though I haven’t been a teenage girl in a good many years I have to say she’s the one that probably would have been the most fun to hang out with in high school.


Being a good ol’ southern girl she confesses a love for Chick-Fil-A, alligators, and sweet tea. Her fans are called the Swamp Family and she even has her own Swamp Family line of t-shirts and accessories on Etsy.

Most of the time we see Bunny looking like this:


or this:

or this:

and only occasionally do we see her looking like this:


The likes of  Scarlett Johansson or Anne Hathaway might indulge in the occassional less than optimal selfie...but as a career habit? Nuh uh. When we see celebrities stripped of makeup or in unflattering poses it tends to be because one of those front racked at the supermarket tabloids snapped them when they weren’t looking, not because they chose to present themselves that way. For Bunny Meyer it’s a big part of her personal brand.

So, not only does Bunny break the beauty and fashion world rules of putting only your best, most fixed up face forward, she also breaks the conventions of YouTube. Her videos are long – most are in the 15 minute range -- whereas most vloggers’ videos run maybe 3 to 4 minutes.  And there’s really something strangely compelling about her videos. She definitely overflows with personality but tell me if you don’t get pulled into listening her to talk about thrift shopping and her recent assaults by retail personnel. 


If she’d had a producer I’m sure s/he would have counselled Bunny to make shorter videos and to pull back the spazziness a few notches, and maybe not do extended monologues about her interest in the paranormal and possible encounters with alien beings. A producer would likely have told her it was off topic and therefore bound to alienate (no pun intended) viewers.

…And that advice would have been a mistake. The result of Bunny doing things Bunny’s way: 3.2 million subscribers and 282 million views as of mid July 2014. She is currently getting a million views a day / 30 million views monthly and is the 750th most popular channel on YouTube according to view count, and 150th for subscriber count. You can see how her channel has grown in popularity in the chart below. Bunny started posting to YouTube at the end of 2010, had a slow 2011, but she kept going, and by 2012 was netting a few million views a month which turned into 10 million views a month by mid 2013 and 30 million views a month by mid 2014.


In total, Bunny has close to 700 videos on her channel and is posting news ones at a rate of 4 to 5 per week, which, which is an ambitious production schedule, and I don’t know if she has assistance with editing or running what is now a small media empire. In other words Bunny is producing about an hour of new video content each week, which, in a TV world would cost in the hundreds of thousands to million range, and involve a crew of a few dozen people. Even if Bunny now has a helper I think it’s safe to say that her costs are considerably lower. Depending on the ad rates she is receiving on YouTube (it varies greatly from channel to channel) she is probably making somewhere between $1000-$5000/day in advertising revenue (of which approximately 45% usually goes to YouTube).

Bunny’s is a career built primarily on two platforms: YouTube, where has a legion of over 3 million followers, and Instagram, where she has close to a million followers. Her numbers on Facebook and Twitter are considerably smaller, about half a million and 250,000 respectively. But that makes perfect sense. Facebook and Twitter are, increasingly, where people’s parents hang out. And brands. Bunny and her followers are about a rejection of the way things are ‘supposed’ to be done and an embracing,  not a covering up of, imperfection, and the weirdo within.

As one of her fans put it :

“…not too long ago I discovered Grav3yardgirl, or Bunny Meyer, and she's one of the most positive internet personalities out there and is SUCH a great role model for girls. I really love how she has odd facial features (not necessarily ugly, but deemed ugly by many people), and she owns the absolute shit out of them and flaunts her confidence. They're what make her unique, and the fact that she's confident despite the nasty comments from other people, makes her all the more beautiful.”
                             
A big part of Bunny’s success online is exactly that; i.e. the way her fans relate to her. Not as someone shaped by managers and agents, not as a product of industry, but as an individual, created by no one other than herself. In earlier times she would not have been able to reach a million people a day operating either largely or entirely on her own, but this is a new world. And it is now competing head to head with the old world. Where things go from here will be interesting to see. Will she continue operating independently as a YouTuber? With the kind of numbers she has I would think this is certainly an option. Will she get offered sponsorship or endorsement deals? I'd be surprised if that hasn't already happened. Will she get cast in a TV show, or her own line of makeup or clothing? All possible. With the hard work of amassing the audience already done, someone like Bunny Meyer, should she be interested, brings the huge value of a built-in audience and a cool-but-not-in-the-usual-way sensibility to any company or product she chooses to work with. But the bigger win is to us, in that 'we the people' kind of way, because Bunny has been successful in adding some elasticity to notions of beauty and cool, which for too long have been unnecessarily rigid and limiting.

Related Posts:

YouTubers in 2015: The appeal of the Annoying Orange and A King of Trivia & a girl-next-door beauty blogger